Pix MED (Special Refund Mechanism): what it is, when to use it, and how the refund works
Fell for a Pix scam? The MED (Special Refund Mechanism, or Mecanismo Especial de Devolução) is the set of rules created by the Central Bank of Brazil to enable the refund of a Pix transaction in cases of fraud and operational failure.
Fell for a Pix scam? The MED (Special Refund Mechanism, or Mecanismo Especial de Devolução) is the set of rules created by the Central Bank of Brazil to enable the refund of a Pix transaction in cases of fraud and operational failure. It doesn't guarantee your money back — but, triggered quickly and the right way, it increases your chances of recovering the amount. In this guide, you'll understand what the MED is, when it can be used, how the analysis and refund flow works, and what the mechanism's real limits are.
Important: this article is educational content and does not constitute individual investment advice or personalized legal guidance.
What is the Pix MED?
The Special Refund Mechanism (Mecanismo Especial de Devolução) is a set of rules and operational procedures created by the Central Bank to enable the refund of a Pix transaction in situations of fraud and operational failure. In practice, it creates a standardized path between banks (the so-called PSPs — Pix participants) to dispute a suspicious transaction and try to return the money to the victim.
It's important not to confuse the MED with a "chargeback guarantee." The mechanism organizes the dispute and blocking process, but the actual refund depends on conditions we'll cover below — mainly, on whether there is a balance in the account that received the money.
When can the MED be triggered?
The MED applies to two types of situations:
- Reasonable suspicion of fraud: when there are signs that the Pix was the result of a scam, a mistake, or misuse of the victim's data.
- Operational failure: when the error stems from a problem in the system's or the institution's own functioning.
Outside these scenarios — for example, when you simply regret a purchase or sent a Pix to the wrong recipient by accident — there may be another path: regardless of the MED, the recipient of a Pix can return the amount on their own initiative within 90 days of the original transaction. Often, direct contact with the person who received the money resolves the case without needing to trigger the formal mechanism.
How the MED flow works: analysis and refund
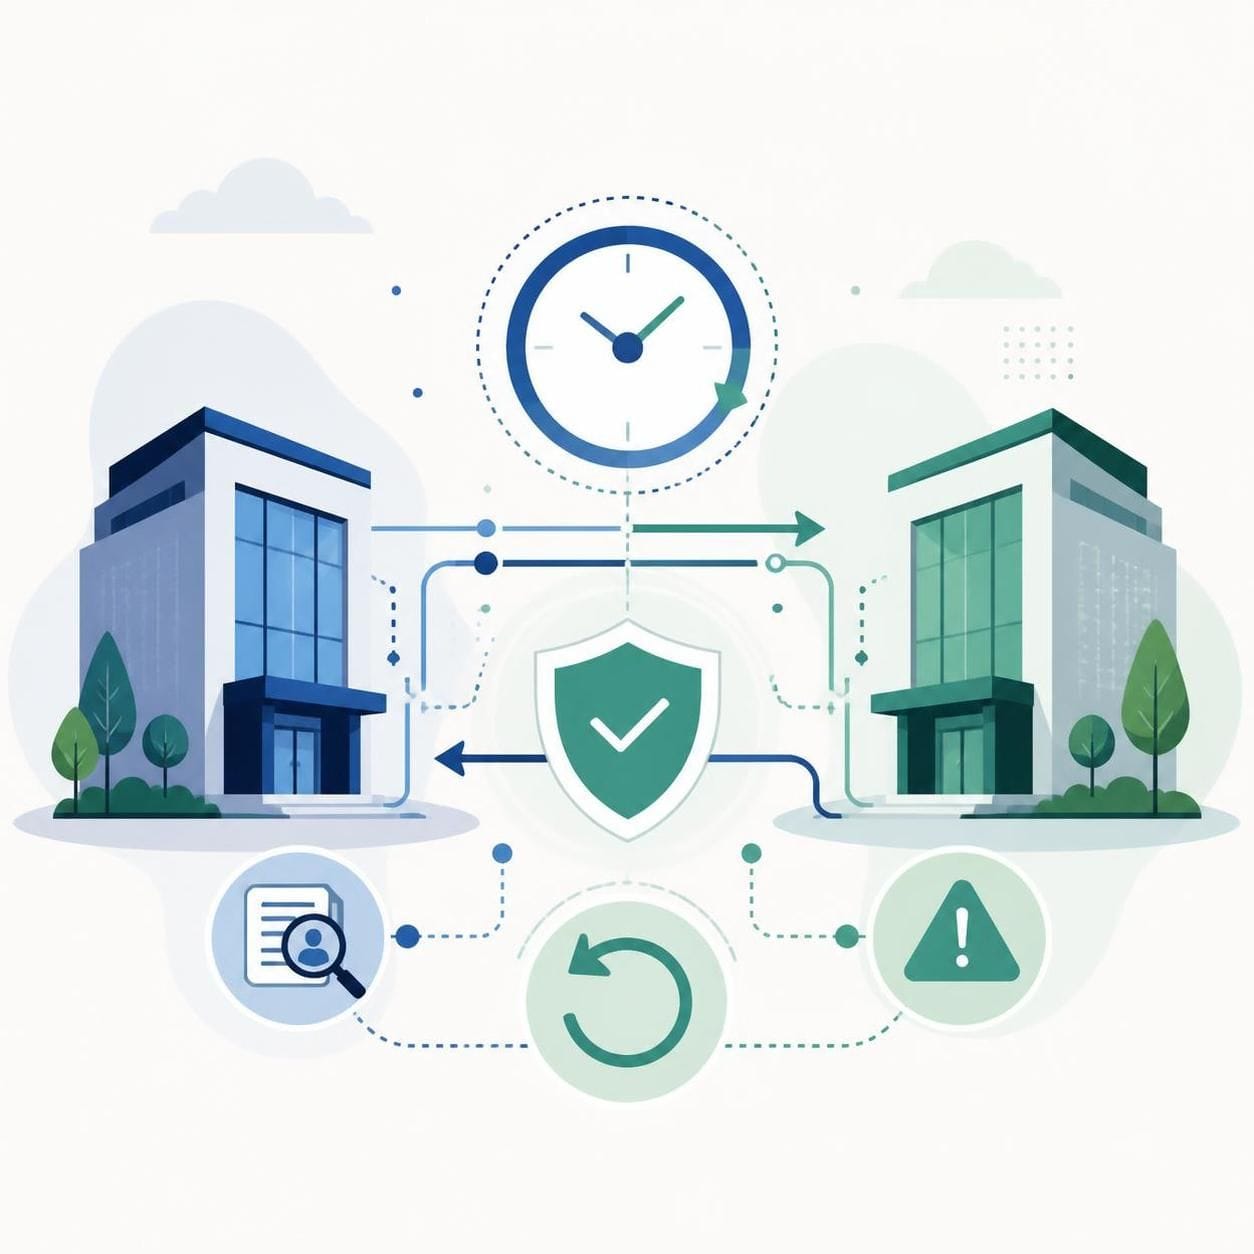
The MED flow follows standardized steps between the payer's bank and the recipient's bank:
- Opening the notification: upon identifying suspected fraud, the payer's bank (the payer's PSP) opens an Infraction Notification (NI) about the transaction.
- Precautionary block: in case of suspected fraud, the recipient's bank may place a precautionary block on the funds for up to 72 hours while it analyzes the case in more detail.
- Analysis of the notification: the recipient's bank evaluates the NI and decides whether to accept or reject the dispute.
- Refund request: if the notification is accepted, the payer has up to 72 hours to request the refund.
If the request is accepted and there are funds available in the recipient's account, the amount is returned to the payer. If the notification is rejected, the case may require other routes, such as filing a police report and contacting the institution directly.
Pay attention to the deadlines: the Central Bank's MED Guide indicates a version 4.4 with effective dates starting on 09/01/2026 and 10/26/2026. This means that deadlines and flow details may change on those dates — always check the most recent official documentation before acting.
Does the MED guarantee my money back?
No — and that's the most important piece of information in this article. The MED does not guarantee the refund of the disputed amount: the refund depends on there being funds in the recipient's account at the time of the block. Scammers typically move the money quickly across multiple accounts, which reduces the chances of recovery.
The Central Bank itself acknowledges this limitation: according to official data presented by the BC, in 2025, on average, 9.3% of the disputed amount was recovered under the MED in effect at the time. Two qualifications are worth highlighting:
- That statistic refers to the MED in effect before MED 2.0 — it is not a projection of future results;
- MED 2.0 extends tracking beyond the first account that received the fraudulent funds, precisely to address this limitation.
In other words: the mechanism is evolving, but the best protection remains prevention — being wary of unexpected charges, confirming details before paying, and using tools like the 24-hour rule before impulsive decisions (see our article on impulse purchases and the 24-hour rule).
MED vs. voluntary refund: what's the difference?
| Aspect | MED | Voluntary refund |
|---|---|---|
| Who decides | Banks, via formal notification | The recipient themselves |
| Applicable scenario | Fraud or operational failure | Any situation, at the recipient's discretion |
| Deadline | Precautionary block of up to 72h; refund request within 72h after acceptance | Up to 90 days from the original transaction |
| Guarantee of recovery | No — depends on the balance in the recipient's account | No — depends on the recipient's goodwill |
The two paths are not mutually exclusive: in many scam cases, the MED is triggered while, in parallel, the victim files a police report and follows up on the case with the bank.
What to do in practice if you fell for a Pix scam
- Act fast: the sooner the case is reported to your bank, the greater the chance the money is still in the first receiving account.
- File the dispute in your bank's app and request the MED be triggered when applicable.
- Keep evidence: receipts, screenshots, conversations. Keeping a routine for organizing receipts helps a lot in these cases (see how to organize financial receipts).
- File a police report, especially in fraud cases.
- Review your security: registered Pix keys, transaction limits, and access credentials. If you don't know which keys are registered under your CPF, you can check via Registrato (see how to find Pix keys registered under your CPF).
Common mistakes when dealing with the MED
- Thinking the MED is a guaranteed refund: as we've seen, the average recovery in 2025 was 9.3% of the disputed amount — the mechanism is a path, not a promise.
- Delaying the dispute: the precautionary block and the refund request have short windows (72 hours), and scammers' money tends to move fast.
- Confusing buyer's remorse with fraud: the MED is for fraud and operational failure, not for changing your mind about a purchase.
- Not tracking rule effective dates: with the updates to MED Guide 4.4 (effective 09/01/2026 and 10/26/2026), deadlines and flows may change.
FAQ
What does MED mean in Pix? It's the Special Refund Mechanism (Mecanismo Especial de Devolução): the set of Central Bank rules to enable the refund of a Pix in cases of fraud and operational failure.
How long can the bank block the recipient's funds? In case of suspected fraud, the recipient's bank may place a precautionary block on the funds for up to 72 hours while it analyzes the notification.
If the MED is accepted, how long do I have to request the refund? If the notification is accepted, the payer has up to 72 hours to request the refund.
Does the MED return 100% of the amount? No. The refund depends on there being funds in the recipient's account. According to the Central Bank, in 2025 the average recovered was 9.3% of the disputed amount.
Can I request a Pix refund without using the MED? Yes. Regardless of the MED, the recipient can return the amount on their own initiative within 90 days of the original transaction.
Conclusion
The Pix MED is the formal path to try to reverse transfers in cases of fraud and operational failure, with a precautionary block of up to 72 hours and a refund request within 72 hours after the notification is accepted. But it is not a guarantee: the refund depends on the balance in the recipient's account, and the average recovered in 2025 was only 9.3% of the disputed amount. That's why speed when disputing, organized evidence, and prevention remain your best tools. And remember: deadlines and flows may change with the effective dates of MED Guide 4.4 — always check the Central Bank's official documentation.
Educational content; it does not constitute individual investment advice.