Payroll-Deducted Loans in Brazil: How They Work, Margins, and Risks
Payroll-deducted loans (empréstimo consignado) are a credit option where loan payments are deducted directly from the borrower's paycheck or social security benefit.
Payroll-deducted loans (empréstimo consignado) are a credit option where loan payments are deducted directly from the borrower's paycheck or social security benefit. Because of this automated mechanism, payroll-deducted credit typically offers some of the lowest interest rates among unsecured personal loan options in Brazil, driven by lower default risk for financial institutions. However, there are strict legal limits on how much income can be committed—known as the payroll margin (margem consignável)—along with distinct risks that must be carefully evaluated before borrowing.
This guide explains how payroll-deducted loans work, who is eligible, general margin rules, advantages, and risks, based on official documents from the Central Bank of Brazil (BCB). This content is educational and does not constitute individual credit advice.
What Is a Payroll-Deducted Loan?
A payroll-deducted loan is a personal credit line where installment payments are withheld directly from a worker’s payroll or a retiree's/pensioner's social security benefit. According to the Central Bank, "loan installments are deducted directly from the borrower's payroll or social security benefit."
This mechanism reduces default risk for lenders because repayment does not rely on the borrower remembering due dates or transferring funds manually. Conversely, income commitment happens automatically, requiring careful financial planning.
Payroll-deducted credit differs from other personal credit lines, such as overdraft protection (cheque especial) and revolving credit card debt, which carry higher costs and lack automated payroll deductions. Comparing their key features highlights these differences:
Payroll Loans vs. Standard Personal Credit vs. Overdraft
| Feature | Payroll-Deducted Loan | Standard Personal Loan | Overdraft Protection |
|---|---|---|---|
| Installment Deduction | Automatic via payroll or benefit | Bank slip or scheduled debit | No fixed installments |
| Lender Guarantee | Future committed income | Depends on credit analysis | Pre-approved limit |
| Default Risk for Lender | Low | Medium | High |
| Typical Cost | Generally lower than other lines | Variable | High |
| Income Commitment | Restricted by payroll margin | No general legal limit | No general legal limit |
The table above is illustrative and does not show specific interest rates, as charges vary by financial institution, borrower category, and market conditions at the time of contracting. To compare the cost of different credit proposals, it is helpful to understand the concept of the Total Effective Cost (CET) on loans, explained in our dedicated guide.
How Payroll Deductions Work
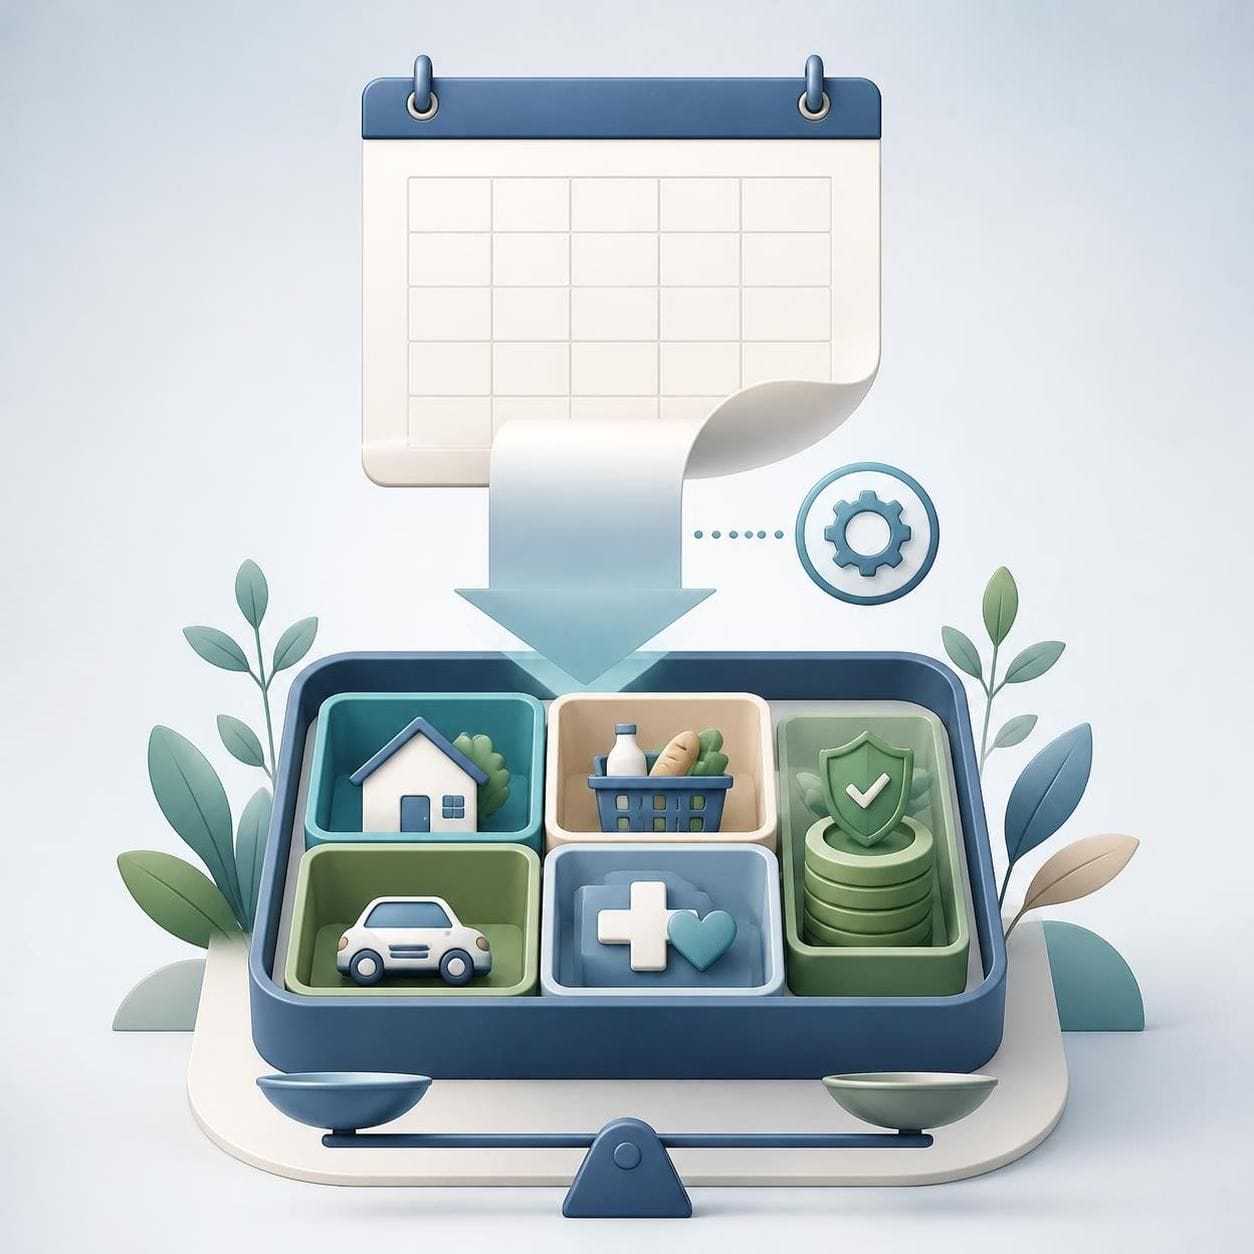
With a payroll-deducted loan, the borrower authorizes the lender to deduct the installment amount directly from their salary or benefit before funds reach their account. This ensures payments occur automatically without monthly manual action.
This model provides predictability: installment amounts are fixed, and deductions occur on the exact payday. However, it permanently reduces available net income each month, which can strain household budgets if other financial commitments exist.
Automatic deductions also require maintaining employment or benefit status. If a worker is laid off, payroll deductions may be interrupted, and the remaining balance must be renegotiated with the financial institution. This is a critical factor for anyone considering payroll credit as a short-term solution.
Before borrowing, review your monthly budget to ensure installments fit comfortably within your net income after deductions. If you are organizing your finances, our complete financial organization guide can help map out income and expenses.
Payroll Margin: How Much Income Can Be Committed?
The payroll margin is the legal limit on the percentage of income that can be committed to payroll-deducted loans. As a general rule, existing regulations limit total income commitment for payroll loans to 35%, which includes 5% specifically allocated for payroll credit cards.
This means that, according to BCB guidelines, up to 35% of available income can be used for payroll loan installments, with 5% reserved for payroll credit cards. However, exact regulations vary depending on the borrower category:
- Private-sector employees under CLT (consolidation of labor laws): Rules established by specific legislation.
- Social security beneficiaries (INSS): Specific INSS regulations.
- Public servants: Specific rules for federal, state, or municipal levels.
The payroll margin exists to protect borrowers from over-indebtedness, preventing their entire income from being tied up in debt. At the same time, this limit restricts the maximum loan amount available: higher income allows for larger loans, provided the ceiling is respected.
If you are facing debt and considering a payroll loan to reorganize your finances, read our guide on how to get out of debt on a low income.
Who Is Eligible for Payroll-Deducted Loans?
Payroll-deducted credit is available to specific groups receiving regular income from a reliable source:
- Retirees and pensioners under INSS.
- Formal private-sector workers (CLT).
- Public servants.
- Military personnel and other statutory positions.
Each group has distinct margin rules and conditions defined by specific laws and normative instructions. Applications must be made through authorized financial institutions, which verify available margins before releasing funds.
Payroll loans are not an automatic right: workers or beneficiaries must request credit from a financial institution, which conducts an analysis and confirms available margins. Lenders may also decline operations if restrictions exist or margins are fully committed.
Advantages of Payroll-Deducted Loans
Key advantages of payroll loans, based on Central Bank documentation and product characteristics, include:
- Generally lower interest rates than other unsecured personal credit lines due to reduced default risk from automated deductions.
- Fixed and predictable installments withheld automatically, simplifying financial planning.
- Reduced bureaucracy in many cases, as income is verified directly through the payroll source.
- Income commitment caps that protect borrowers from pledging their entire salary.
These benefits make payroll loans an option frequently considered for paying off more expensive debts, such as revolving credit card balances or overdrafts. Nevertheless, evaluating the total cost and repayment capacity beforehand is essential.
Risks and Disadvantages
Despite lower interest rates, payroll-deducted loans carry significant risks:
- Long-term income reduction: automatic deductions lower monthly net income, which can complicate covering other essential expenses.
- Risk of over-indebtedness: even with margin limits, borrowers can accumulate other debts that, combined with payroll deductions, overwhelm their budget.
- Loss of employment: job termination halts payroll deductions, requiring balance renegotiation, often under less favorable conditions.
- Difficulty of cancellation: payroll loans cannot simply be "canceled" like a service subscription; early settlement involves specific lender conditions.
A payroll loan is a credit tool, not an investment. It carries no promise of returns or financial gains—the cost of credit must be weighed against genuine resource needs.
Are Payroll Loans Worth It?
Payroll loans are worth considering when borrowers have stable income, need credit at lower costs than alternative lines, and can comfortably fit installments into their budgets without jeopardizing essential expenses. In such scenarios, they can serve as a viable alternative to clear expensive debts or fund specific objectives.
They are not advisable when income is already overextended, when repayment capacity is uncertain, or when funds are intended for impulse consumption. In those cases, reorganizing personal finances is the proper first step.
Your decision should account for:
- Do installments fit your monthly net income?
- Is total debt commitment (payroll loan + other debts) sustainable?
- Is the credit earmarked for a clear objective or covering recurring expenses?
- Are there cheaper or more appropriate alternatives available?
If you are evaluating payroll loans to pay off credit card debt, review how revolving credit card rules work and overdraft protection costs, which typically carry much higher rates.
Common Mistakes When Contracting Payroll Loans
Frequent errors can turn an apparently low-cost credit line into a financial burden:
- Comparing proposals solely by interest rates: real loan costs can include fees beyond interest. Evaluate full proposals before deciding; our guide on Total Effective Cost (CET) details this concept.
- Pledging your entire margin: using all available limits at once prevents future borrowing capacity and tightens budgets.
- Borrowing to pay debts without changing habits: without adjusting underlying budgets, payroll loans only postpone financial trouble.
- Ignoring employment termination impacts: interrupted payroll deductions can trigger unfavorable debt renegotiations.
- Disregarding total income commitment: stacking payroll loans with other debts can lead straight to severe over-indebtedness.
FAQ
What is a payroll-deducted loan?
It is a credit modality where loan installments are deducted directly from the borrower's payroll or social security benefit, as described by the Central Bank.
What is the payroll margin limit?
General regulations limit income commitment for payroll loans to 35%, including 5% for credit cards. However, specific rules vary by borrower category (CLT, INSS, public servants), requiring consultation with official sources.
Do payroll loans feature lower rates than standard personal credit?
Payroll-deducted loans typically present lower interest rates than other unsecured personal credit lines. However, rates vary by institution and borrower category, making cost comparisons essential.
Can I cancel a payroll loan after contracting it?
Payroll loans cannot be canceled like a service subscription. Early settlement is possible, but conditions vary by financial institution. Check your contract and lender for specific rules.
What happens if I am fired?
Payroll deductions stop, and the remaining balance must be renegotiated with the financial institution, often under less favorable terms. Anticipating this scenario is crucial before borrowing.
Conclusion
Payroll-deducted loans provide credit with automated paycheck or benefit deductions, reducing lender risk and usually resulting in lower rates. The payroll margin limits income commitment—general rules cap it at 35% (including 5% for credit cards), though percentages vary by borrower category.
Before signing, evaluate installment fit, total debt commitment, and credit purpose. Payroll loans are credit tools, not investments, and require careful planning. Consult the Central Bank and your financial institution to confirm applicable rules.
To deepen your knowledge, read our complete financial organization guide.
Educational content; does not constitute individual credit advice.